An extra $300 a month can give you breathing room. Deciding where to put it can be harder. Should you reduce your credit-card balance, build your savings, or contribute more to your 401(k)?
For U.S. workers in their 20s and 30s, capturing an employer match can be a sensible priority once essential expenses, minimum debt payments, and a small cash cushion are covered. But the answer changes if your income is unstable, you are behind on bills, or you may leave your job before the match becomes yours.
 Retirement can feel impossibly far away when you’re in your 20s or 30s. Between rent, student loans, travel plans, career changes, and trying to enjoy life now, putting money aside for a future that’s decades away rarely feels urgent.
 When inflation rises, everyday life becomes noticeably more expensive. Groceries cost more, rent increases, gas prices climb, and monthly bills stretch paychecks thinner than before.
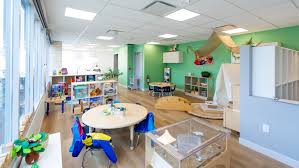 Childcare is one of the largest expenses many families face. Between daycare tuition, babysitters, after-school programs, and summer care, costs can quickly strain a household budget. While quality childcare is essential, there are practical ways to reduce expenses without sacrificing safety or reliability.
 Extracurricular activities help children build confidence, learn new skills, and make friends—but the costs can add up quickly. Between registration fees, uniforms, equipment, and travel expenses, families often feel pressure to spend more than they planned. Fortunately, there are several practical ways to keep costs manageable without limiting your child’s opportunities.